The scenario being laid out by William O'Neil for the next upward super-cycle in the stock market is most interesting. I hope he is right. I'm not getting any younger.
I place Mr. O'Neil up there with the likes of Michael Burry, Jim Rogers, Victor Niederhoffer, Dave Davidson, David Ryan and afew others. It's been 30 years since his big score in Price Club (COSTCO) shares which helped him launch our "bible" here at Chippewa Partners, Investors Business Daily. The methodology will always work. If and only if you do the work.
And again, a huge tip of the hat to Dave Davidson in San Francisco.
Wednesday, October 31, 2012
Sunday, October 28, 2012

4th Quarter earnings........
Know doubt about it. Every company with weak numbers this quarter has to be lining up to blame Hurricane Sandy for the miss. Can't you hear the phone calls? The whispers in the board room? Directors using cell phones to ask questions about what kind of blame they can lay at the hands of sustained winds?
Everybody. Looking for the perfectly legitimate excuse.
It gets old.
Everybody. Looking for the perfectly legitimate excuse.
It gets old.
Thursday, October 25, 2012
Maybe it really isn't different this time.........
Go to any university, any center of equities trade, any meeting place for
financial academia, any fiscal think tank, and they will tell you without the
slightest hint of doubt in their eyes that the U.S. economy is essential
to the survival of the world. To even broach the possibility that the
U.S. could be dropped or replaced as the central pillar of trade on the planet
is greeted with sneers and even anger. Whether it's deleveraging, spare
capacity, dollar debasement, productivity gains, or just plain old obesity, in
real purchasing power terms, an hour of your time has never been worth
less. In the 40 years since Nixon's 1971 fiat-fiasco, the value of the
average hourly earnings for US citizens has dropped 90% in terms of Gold.
Since the peak in 2001, 60 minutes of your valuable time has lost
81% of its purchasing power! Is this what globalization looks
like?
lil humor.............
A woman was playing golf when she took a big swing and
fell.
The party waiting behind her was a group from
the White House that included Obama. Obama quickly stepped forward and helped her to her
feet.
She thanked him and started to leave, when he
said, "I'm President Obama and I hope you'll vote for me this
November."
She laughed and quickly said, "I fell on my ass, not my
head!"
Wednesday, October 24, 2012
Massive Difference in Obama Romney voters
So, if someone asks you what the main difference is between most of the Obama
supporters, and Romney supporters, instead of stammering, and stuttering, and
looking for an answer, just tell them that the Romney supporters sign their
checks on the front, and the Obama supporters sign their
checks on the back.
Tuesday, October 23, 2012
Gimme, gimme in Native America
Native American Advisors, Inc. has been a success since inception. In many ways.
Over the years on the desk I have taken some very weird phone calls. Very weird. Usually it is someone thinking we deal in Native American jewelry. Or somehow we have a conduit to the money spiggots of some Native American casino (that is profitable). Hardly. That really strikes me as funny as I type this.
Many times it is a poor lost soul looking for a hand-out, never a hand-up. And yes, we have helped on occasion.
The conversation generally goes like this. The phone rings, I answer. I can tell by the voice inflection it is a "minority" immediately. I am then told they have a grandmother, or aunt or grandfather or some shirt-tail relative who was Cherokee. They never can tell me if they might be Eastern Band or Western Band. They just want to know how they can get that "free money" that they hear about if someone might be a member of a "real" tribe. (Unlike a nonreal tribe?)
To hear the wind come out of their inquiry is rather amusing. The something-for-nothing crowd is alive and well in America. Maybe, just maybe, things can turn in the next couple of weeks. And I am not talking hope or change.
Over the years on the desk I have taken some very weird phone calls. Very weird. Usually it is someone thinking we deal in Native American jewelry. Or somehow we have a conduit to the money spiggots of some Native American casino (that is profitable). Hardly. That really strikes me as funny as I type this.
Many times it is a poor lost soul looking for a hand-out, never a hand-up. And yes, we have helped on occasion.
The conversation generally goes like this. The phone rings, I answer. I can tell by the voice inflection it is a "minority" immediately. I am then told they have a grandmother, or aunt or grandfather or some shirt-tail relative who was Cherokee. They never can tell me if they might be Eastern Band or Western Band. They just want to know how they can get that "free money" that they hear about if someone might be a member of a "real" tribe. (Unlike a nonreal tribe?)
To hear the wind come out of their inquiry is rather amusing. The something-for-nothing crowd is alive and well in America. Maybe, just maybe, things can turn in the next couple of weeks. And I am not talking hope or change.
Monday, October 22, 2012
What I thought funny.......
A man that has NEVER balanced a budget is telling a man that ALWAYS balanced his budgets that his ideas won't work?
Jordan Stone Parisian, 2012
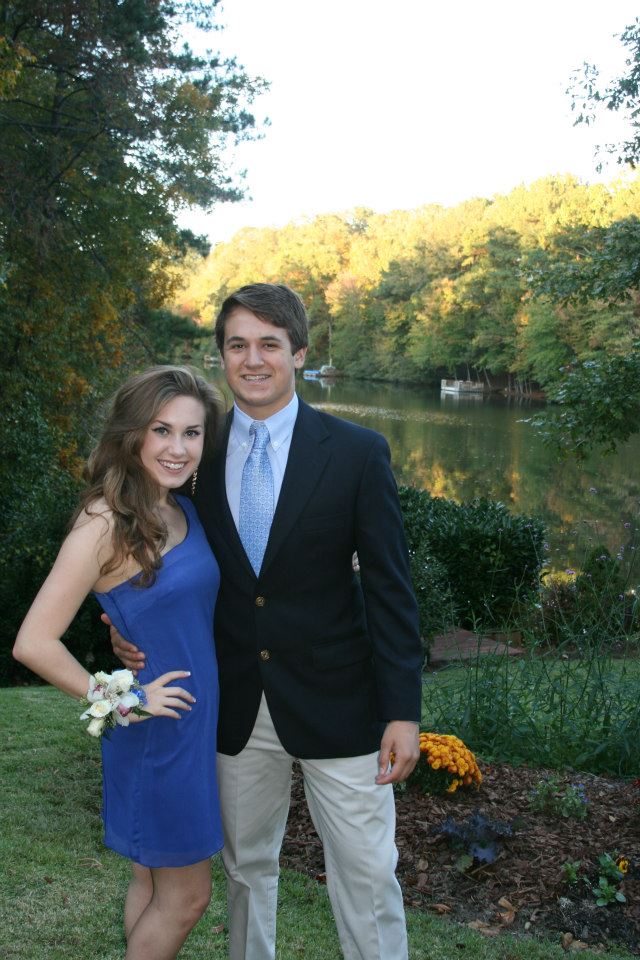
Jordan enjoyed a wonderful evening with friends at Homecoming his sophomore year at Milton High School. What a great group they are, lean, mean and the class of 2015!
No truer words were ever spoken...............
Getting an unsophisticated client is the golden prize," Greg Smith told Anderson Cooper. "The quickest way to make money on Wall Street is to take the most sophisticated product and try to sell it the least sophisticated client."
Monday, the 22nd of October, 2012
Once in a great while it's okay to reflect and smell the roses.
When a guy is firing on all cyclinders it just feels good. Dam good.
Congratulations to all the clients of Native American Advisors, Inc.
When a guy is firing on all cyclinders it just feels good. Dam good.
Congratulations to all the clients of Native American Advisors, Inc.
Milton Homecoming, 2012

My son, Jordan, has the nicest friends. This picture was their idea and thank you girls for allowing Mr. Dean into the picture!
Greg Smith, formerly of Goldman Sachs
Honest.
Which is more that you can say about Paulsen, Blankfein or Corzine.
Which is more that you can say about Paulsen, Blankfein or Corzine.
Sunday, October 21, 2012
Obama Logic..........
COSTELLO:
I want you to explain about the unemployment rate in America.
ABBOTT: Good Subject. Terrible Times. It's 8.1%.
COSTELLO: Wow! That’s so many people out of work!
ABBOTT: No, that's 16%.
COSTELLO: You just said 8.1%.
ABBOTT: 8.1% are Unemployed.
COSTELLO: Right 8.1% out of work.
ABBOTT: No, that's 16%.
COSTELLO: Okay, so it's 16% unemployed.
ABBOTT: No, that's 8.1%.
COSTELLO: WAIT A MINUTE. Is it 8.1% or 16%?
ABBOTT: 8.1% are unemployed. 16% are out of work.
COSTELLO: IF you are out of work you are unemployed.
ABBOTT: No, Obama said you can't count the "Out of Work" as the unemployed. You have to look for work to be unemployed.
COSTELLO: But they ARE out of work!!
ABBOTT: No, you are missing his point.
COSTELLO: What point?
ABBOTT: Someone who doesn't look for work can't be counted with those who look for work. It wouldn't be fair.
COSTELLO: To whom?
ABBOTT: The unemployed.
COSTELLO: But they are ALL out of work.
ABBOTT: No, the unemployed are actively looking for work. Those who are out of work gave up looking and if you give up, you are no longer in the ranks of the unemployed.
COSTELLO: So if you're off the unemployment rolls, that would count as less unemployment?
ABBOTT: Absolutely! Unemployment would go down.
COSTELLO: The unemployment goes down just because you don't look for work?
ABBOTT: Right! That's how Obama gets it to 8.1%. Otherwise it would be 16%. He doesn't want you to read about 16% unemployment.
COSTELLO: That would be tough on his reelection.
ABBOTT: You got it.
COSTELLO: Wait, I got a question for you. That means there are two ways to bring down the unemployment number?
ABBOTT: Two ways – that’s right.
COSTELLO: Unemployment can go down if someone gets a job?
ABBOTT: Correct.
COSTELLO: And unemployment can also go down if you stop looking for a job?
ABBOTT: Bingo.
COSTELLO: So there are two ways to bring unemployment down, and the easier of the two is to have Obama's supporters stop looking for work.
ABBOTT: Now you're thinking like the Obama Economy Czar.
COSTELLO: I don't even know what the hell I just said!
ABBOTT: Now you're thinking like Obama….
ABBOTT: Good Subject. Terrible Times. It's 8.1%.
COSTELLO: Wow! That’s so many people out of work!
ABBOTT: No, that's 16%.
COSTELLO: You just said 8.1%.
ABBOTT: 8.1% are Unemployed.
COSTELLO: Right 8.1% out of work.
ABBOTT: No, that's 16%.
COSTELLO: Okay, so it's 16% unemployed.
ABBOTT: No, that's 8.1%.
COSTELLO: WAIT A MINUTE. Is it 8.1% or 16%?
ABBOTT: 8.1% are unemployed. 16% are out of work.
COSTELLO: IF you are out of work you are unemployed.
ABBOTT: No, Obama said you can't count the "Out of Work" as the unemployed. You have to look for work to be unemployed.
COSTELLO: But they ARE out of work!!
ABBOTT: No, you are missing his point.
COSTELLO: What point?
ABBOTT: Someone who doesn't look for work can't be counted with those who look for work. It wouldn't be fair.
COSTELLO: To whom?
ABBOTT: The unemployed.
COSTELLO: But they are ALL out of work.
ABBOTT: No, the unemployed are actively looking for work. Those who are out of work gave up looking and if you give up, you are no longer in the ranks of the unemployed.
COSTELLO: So if you're off the unemployment rolls, that would count as less unemployment?
ABBOTT: Absolutely! Unemployment would go down.
COSTELLO: The unemployment goes down just because you don't look for work?
ABBOTT: Right! That's how Obama gets it to 8.1%. Otherwise it would be 16%. He doesn't want you to read about 16% unemployment.
COSTELLO: That would be tough on his reelection.
ABBOTT: You got it.
COSTELLO: Wait, I got a question for you. That means there are two ways to bring down the unemployment number?
ABBOTT: Two ways – that’s right.
COSTELLO: Unemployment can go down if someone gets a job?
ABBOTT: Correct.
COSTELLO: And unemployment can also go down if you stop looking for a job?
ABBOTT: Bingo.
COSTELLO: So there are two ways to bring unemployment down, and the easier of the two is to have Obama's supporters stop looking for work.
ABBOTT: Now you're thinking like the Obama Economy Czar.
COSTELLO: I don't even know what the hell I just said!
ABBOTT: Now you're thinking like Obama….
So you want to be spoon-fed?
I was at a party not long ago. Great people, great food. Invariably, when in the midst of people who know what I do for a living, the conversation will turn to stocks and the market.
As the evening wore on, there was a guy who was looking for a hot tip. There is always one in the crowd. Somebody, somewhere looking for the holy grail on a Saturday night.
With cocktail in hand he closed in for the big kill.
Unfortunately, for him, this is what I told him.
I told him big profits come from chaos.
I told him life isn't fair. Accept it for what it is and exploit what the world offers you.
And because he was a "do-it-yourselfer", not wanting to pay for the services of a professional money manager I told him to commit to educate himself as opportunities present themselves.
He walked away extremely disappointed. He had not a clue.
Friday, October 19, 2012
October 19th, 25 years ago
On this day in 1987 (that's 25 years ago, if you are burdened with a
graduate degree), the NYSE had one of its most dramatic trading days in its 220
year history.
It suffered its largest single day percentage loss (22%) and its largest one day point loss up until that day (508 points). Anyone who was in the securities business that day will never forget it.
While it was an unforgettable single day, there were months of events that went into its making. The first two-thirds of 1987 were nothing other than spectacular on Wall Street. From New Year to shortly before Labor Day, the Dow rallied a rather stunning 43%.
Fear seemed to disappear. One thing that also helped banish fear was a new process called "portfolio insurance". It involved use of the newly expanded S&P futures. Somewhat counterintuitively, it involved selling when prices turned down.
The rally topped out about August 25th with the Dow hitting 2722. Interest rates had begun creeping up amid concerns of early signs of inflation.
Treasury Secretary Baker began a rather open debate with the Germans on the relationship of the dollar and the Dmark. Soon the weakness in the market was turning into a visible correction. By the middle of October, the Dow fell to break an uptrend line that had protected it for over 1000 points. The flurry of takeovers and leveraged buyouts that had flourished all year began to dry up.
On Wednesday, October 14th, there were widely discussed rumors of a new punitive tax on takeover profits. Selling turned a bit ugly and the Dow fell 96 points by the close (a record point drop at the time). The next day there was no bounce and the Dow fell another 58 points.
Friday, the 16th was an option expiration day. There was a very bad storm in London and that market closed, which forced more people to seek liquidity in New York. Stocks faced a steady wave of selling. As the close neared, rumors spread that the First Lady, Nancy Reagan, the President's right hand, might be admitted to the hospital with cancer. The selling intensified and the Dow closed down 108 points, on the low and a new record point drop. At 4:01 I left the office to pick up my date and head to the airport. My pal, Budd Zuckerman and I had chartered a small plane to fly to Catalina Island and retrieve his 46 footer, "Flatulyn" and sail back to San Diego on Sunday. Our dates were in for more then they bargained for!
The weekend was a rumormonger's delight. Nancy was admitted to the hospital.
Japan was considering a confiscatory 96% tax on real estate speculation. Germany proposed a change in taxes on some interest rates, which would make U.S. Treasuries unattractive to Germans. Rep. Gephardt was talking about a trade bill that would freeze imports. Treasury Secretary Baker went on a Sunday talk show and openly challenged the Germans on currency. There were even rumors of U.S. planes engaging Iran.
Our office manager, Walter J. Shaw presided over our early morning meeting on Monday. You could cut the fear with a knife. There was going to be a tremendous amount of money "lost" that day. Walter was a great broker and a good manager. He told the troops to keep him informed of any situation where margin calls could be enough to cause accounts to be "sold-out".
From here let me retell the story that I wrote a mere 5 years ago. It seems like only yesterday.
It suffered its largest single day percentage loss (22%) and its largest one day point loss up until that day (508 points). Anyone who was in the securities business that day will never forget it.
While it was an unforgettable single day, there were months of events that went into its making. The first two-thirds of 1987 were nothing other than spectacular on Wall Street. From New Year to shortly before Labor Day, the Dow rallied a rather stunning 43%.
Fear seemed to disappear. One thing that also helped banish fear was a new process called "portfolio insurance". It involved use of the newly expanded S&P futures. Somewhat counterintuitively, it involved selling when prices turned down.
The rally topped out about August 25th with the Dow hitting 2722. Interest rates had begun creeping up amid concerns of early signs of inflation.
Treasury Secretary Baker began a rather open debate with the Germans on the relationship of the dollar and the Dmark. Soon the weakness in the market was turning into a visible correction. By the middle of October, the Dow fell to break an uptrend line that had protected it for over 1000 points. The flurry of takeovers and leveraged buyouts that had flourished all year began to dry up.
On Wednesday, October 14th, there were widely discussed rumors of a new punitive tax on takeover profits. Selling turned a bit ugly and the Dow fell 96 points by the close (a record point drop at the time). The next day there was no bounce and the Dow fell another 58 points.
Friday, the 16th was an option expiration day. There was a very bad storm in London and that market closed, which forced more people to seek liquidity in New York. Stocks faced a steady wave of selling. As the close neared, rumors spread that the First Lady, Nancy Reagan, the President's right hand, might be admitted to the hospital with cancer. The selling intensified and the Dow closed down 108 points, on the low and a new record point drop. At 4:01 I left the office to pick up my date and head to the airport. My pal, Budd Zuckerman and I had chartered a small plane to fly to Catalina Island and retrieve his 46 footer, "Flatulyn" and sail back to San Diego on Sunday. Our dates were in for more then they bargained for!
The weekend was a rumormonger's delight. Nancy was admitted to the hospital.
Japan was considering a confiscatory 96% tax on real estate speculation. Germany proposed a change in taxes on some interest rates, which would make U.S. Treasuries unattractive to Germans. Rep. Gephardt was talking about a trade bill that would freeze imports. Treasury Secretary Baker went on a Sunday talk show and openly challenged the Germans on currency. There were even rumors of U.S. planes engaging Iran.
Our office manager, Walter J. Shaw presided over our early morning meeting on Monday. You could cut the fear with a knife. There was going to be a tremendous amount of money "lost" that day. Walter was a great broker and a good manager. He told the troops to keep him informed of any situation where margin calls could be enough to cause accounts to be "sold-out".
From here let me retell the story that I wrote a mere 5 years ago. It seems like only yesterday.
Friday, October 19, 2007
20 years ago today...............
October 19, 1987. 508 points. A 22% decline. Record volume.
Looking back it was a tremendous buying opportunity. As all steep market corrections have been in your lifetime and mine. Just step in, buy the market and give it time. That October day found me in the offices of Drexel Burnham Lambert in LaJolla, California where I had been a stockbroker for several years. I spent that preceding weekend on an adventure to ease the drama. Friday afternoon I met my pal, Budd Zuckerman at a San Diego airport with our dates and hopped in a chartered plane for a 40 minute run out to Catalina Island. We were late getting together and the pilot was in a hurry to get in the air and get out to Catalina as there were no lights on the Island's airstrip. It was a great weekend with plenty of great food and cold beer and our dates were alot of fun. The boat had been out there for a few weeks and we were to sail it back to San Diego for the partnership that owned it.
Early Sunday we left the yacht basin a little after 4 a.m. for the sail on the 46 foot Flatulyn back to San Diego. It was a little scary as once you left the confines of the marina there wasn't any coming back in until daylight arrived if engine trouble (fire) developed. And no shortage of sharks off of Catalina. And there aren't any lights on the open ocean to guide the way! We had no GPS, no cell phones, no marine emergency radios. Just a compass with no backup, some bravado, our dates and our youth. What else do you need? It was a cool, very cloudy sail until mid afternoon and the clouds were so thick it was virtually impossible to tell where the sun was. There were many many beautiful songbirds on migration virtually "lost" on the open ocean as they couldnt' detect the sun's position and they were landing on every piece of kelp sticking out on the ocean surface as well as all over the boat. We arrived back in San Diego before dark and readied ourselves for what was to be a wild day.
We had our morning meeting at 6 a.m. led by our branch manager, Walter J. Shaw, who has since gone on ahead. Walter did a great job in that meeting. He asked us all to keep him abreast of any major unsecured debits or margin issues in client accounts that were likely to crop up in a further downdraft. We all knew to a man there was going to be some major selling pressure after the Friday rumble of 108 points and a 4.8% drop.
With the market opening it was clear to see that specialists were inundated with selling. Stocks were being opened in big gaps down. As wire communication to the floor became impossible, phone orders were being the norm. And there were probably hundreds of thousands of phone calls that day to trading desks that went unanswered. Traders wouldn't trade. Phones were not being picked up. Notices of trade fills on either buys or sells were hours late. Hours. No specialist firm under the sun was going to commit their own capital when selling of this magnitude was staring them in the bottom line.
That day I had several clients wade into the abyss and just buy some blue-chips. Small trades but more buying than selling. As the day wore on it became apparent the system was in trouble. My livlihood was threatened. Was the NYSE on the verge of collapse? Where would we work? What would I do?
I remember so clearly sitting in the office of my great friend, Maurice Altshuler, who is still a broker with the venerable brokerage house of Morgan Stanley in LaJolla. Maurice and I talked about the future, what could happen and never without any fear for ourselves as to having a career or a job or doing something else. Little did I know that Maurice had over a $1,000,000,000 unsecured debit from a new client in Switzerland who had opened an account the previous week and put the money to work. It wasn't pretty then and could have been a nasty situation. Maurice handled it like he does with about everything else in life, with grace, dignity and professionalism.
The market soon recovered. 1987 was a year to remember. It was the year the government fingered Ivan Boesky and when Boyd Jefferies handed over his firm. It was a year to remember. And a heck of a year to put money in the stock market.
To buy them when no one else wants them. To buy when the baby is getting thrown out with the bathwater. Just buy the market. And sit until you need the money.
Looking back it was a tremendous buying opportunity. As all steep market corrections have been in your lifetime and mine. Just step in, buy the market and give it time. That October day found me in the offices of Drexel Burnham Lambert in LaJolla, California where I had been a stockbroker for several years. I spent that preceding weekend on an adventure to ease the drama. Friday afternoon I met my pal, Budd Zuckerman at a San Diego airport with our dates and hopped in a chartered plane for a 40 minute run out to Catalina Island. We were late getting together and the pilot was in a hurry to get in the air and get out to Catalina as there were no lights on the Island's airstrip. It was a great weekend with plenty of great food and cold beer and our dates were alot of fun. The boat had been out there for a few weeks and we were to sail it back to San Diego for the partnership that owned it.
Early Sunday we left the yacht basin a little after 4 a.m. for the sail on the 46 foot Flatulyn back to San Diego. It was a little scary as once you left the confines of the marina there wasn't any coming back in until daylight arrived if engine trouble (fire) developed. And no shortage of sharks off of Catalina. And there aren't any lights on the open ocean to guide the way! We had no GPS, no cell phones, no marine emergency radios. Just a compass with no backup, some bravado, our dates and our youth. What else do you need? It was a cool, very cloudy sail until mid afternoon and the clouds were so thick it was virtually impossible to tell where the sun was. There were many many beautiful songbirds on migration virtually "lost" on the open ocean as they couldnt' detect the sun's position and they were landing on every piece of kelp sticking out on the ocean surface as well as all over the boat. We arrived back in San Diego before dark and readied ourselves for what was to be a wild day.
We had our morning meeting at 6 a.m. led by our branch manager, Walter J. Shaw, who has since gone on ahead. Walter did a great job in that meeting. He asked us all to keep him abreast of any major unsecured debits or margin issues in client accounts that were likely to crop up in a further downdraft. We all knew to a man there was going to be some major selling pressure after the Friday rumble of 108 points and a 4.8% drop.
With the market opening it was clear to see that specialists were inundated with selling. Stocks were being opened in big gaps down. As wire communication to the floor became impossible, phone orders were being the norm. And there were probably hundreds of thousands of phone calls that day to trading desks that went unanswered. Traders wouldn't trade. Phones were not being picked up. Notices of trade fills on either buys or sells were hours late. Hours. No specialist firm under the sun was going to commit their own capital when selling of this magnitude was staring them in the bottom line.
That day I had several clients wade into the abyss and just buy some blue-chips. Small trades but more buying than selling. As the day wore on it became apparent the system was in trouble. My livlihood was threatened. Was the NYSE on the verge of collapse? Where would we work? What would I do?
I remember so clearly sitting in the office of my great friend, Maurice Altshuler, who is still a broker with the venerable brokerage house of Morgan Stanley in LaJolla. Maurice and I talked about the future, what could happen and never without any fear for ourselves as to having a career or a job or doing something else. Little did I know that Maurice had over a $1,000,000,000 unsecured debit from a new client in Switzerland who had opened an account the previous week and put the money to work. It wasn't pretty then and could have been a nasty situation. Maurice handled it like he does with about everything else in life, with grace, dignity and professionalism.
The market soon recovered. 1987 was a year to remember. It was the year the government fingered Ivan Boesky and when Boyd Jefferies handed over his firm. It was a year to remember. And a heck of a year to put money in the stock market.
To buy them when no one else wants them. To buy when the baby is getting thrown out with the bathwater. Just buy the market. And sit until you need the money.
Thursday, October 18, 2012
CHIPPEWA PARTNERS
I am the Chairman of Chippewa Partners which
is a private investment management firm.
We are money managers. We manage investments across the globe for
some very wealthy people, and, for some individuals who are much less
fortunate. Now, let me tell you what we are
really about. We’re about doing the
right thing, the right way, for the right reasons for clients who don’t have
the time, training, temperament or discipline to establish and reach specific
goals for the growth and preservation of their assets.
We plan for the attainment of your goals, and
we devise a strategy that is appropriate to reach them. We set the investment
policy in writing, then we execute the strategy. In broad outline, our strategy is to create a
professionally managed account that could encompass two major themes.
The first point is very simple. I believe in a strategy based upon a
combination of passive and active investments.
Study after study reflects what we all know: for the long-term investor, index funds
outperform actively managed mutual funds more than 90% of the time.
My second point is that we spread the
different risks and balance the volatility.
We have a lot of strengths to offer and are
very good at helping clients define their goals, create rational strategies to
meet those goals, and select solid investments to handle each portfolio segment. Let me be clear, we want to get you where you
want to go, but we’d rather you not get there via a roller coaster.
I want to
make a commitment that if you decide to hire Chippewa Partners, throughout
all the years we work together, you will never find another investment advisory
firm who will care more about you and your family, or who’ll be more committed
to the realization of your financial goals. I promise to invest your capital as
carefully as I do my own, because your hopes for the future are every bit as
sacred to you, as mine are to me.
I commit to tell you the plain, unvarnished
truth all the time, especially, when you may not want to hear it. Nor will I tell you I’ll do something and
then not do it.
In interviewing prospective investment
managers you may run across stockbrokers who say they are cheaper than Chippewa
Partners, a Registered Investment Advisor and fiduciary, because frankly, we
are not cheap. But know one thing. You’ll
never in your life find an advisory firm you can trust more than you can trust us
. We insist our clients plan, and stick to their goals; their
goals, not ours.
Clients understand that the serious money we
manage for them is serious business. It deserves serious attention. Clients recognize that what distinguishes us
is that our assignment to manage their investments is not just about portfolio
growth but about their goals, retirements, hopes, dreams and to improve the
quality of their lives.
We invite you to meet with us.
Unfortunately..........
Retail investors listen to brokers, brokers listen to analysts, analysts listen to strategists and strategists often listen to academics.
Wednesday, October 17, 2012
Barry's investment prowess!!!!
It will come as no surprise to some but the bankruptcy court hearing for
Solyndra just threw up all over any hopes that our taxpayer-funded loans to this
solar sinkhole will be recovered:
- *SOLYNDRA HAS ABOUT $71 MILLION IN NET DISTRIBUTABLE ASSETS
- *SOLYNDRA LENDERS AHEAD OF GOVERNMENT OWED ABOUT $77 MILLION
Monday, October 15, 2012
You can't make this stuff up ...........
Jim Bullard, of the St. Louid Federal Reserve is
a non-voting member of the FOMC this year is the same guy who in 2010 was the
first Fed official to call for a second round of QE. He just said
the following:
Fed’s Bullard Says He’s Concerned About Low Returns to Savers
This is similar to Stalin saying, several days after completing the purges which saw tens of millions of people quietly "disappeared", that he is concerned that the price of graveyard real estate might be in a bubble.
Fed’s Bullard Says He’s Concerned About Low Returns to Savers
This is similar to Stalin saying, several days after completing the purges which saw tens of millions of people quietly "disappeared", that he is concerned that the price of graveyard real estate might be in a bubble.
Sunday, October 14, 2012

Debt Facts, just the facts.......
For all intents and purposes, there have been two US Presidents thus far in the
21st century - George Bush (the younger) and Barack Obama. If we take Mr Bush’s
two terms to cover fiscal 2001 to fiscal 2008, the total rise in official
Treasury funded debt over that period was $US 4.350 TRILLION.
If we take Mr Obama’s first term to cover fiscal 2009 to fiscal 2012, the rise over four years was $US 6.050 TRILLION.
Add the two together and you get a grand total of $US 10.4 TRILLION. That’s almost two thirds (65 percent) of the total funded debt of $US 16.066 TRILLION as of September 28, 2012.
If that thieving isn't enough, get a handle on this security fiasco.....
From AP: "Federal authorities are warning merchants to be on the lookout for stolen $100 bills that aren't supposed to go into circulation until next year. The bills were stolen from an airplane that landed in Philadelphia from Dallas Thursday morning. The plane had been transporting money from the Federal Reserve facility in Dallas."
If we take Mr Obama’s first term to cover fiscal 2009 to fiscal 2012, the rise over four years was $US 6.050 TRILLION.
Add the two together and you get a grand total of $US 10.4 TRILLION. That’s almost two thirds (65 percent) of the total funded debt of $US 16.066 TRILLION as of September 28, 2012.
If that thieving isn't enough, get a handle on this security fiasco.....
From AP: "Federal authorities are warning merchants to be on the lookout for stolen $100 bills that aren't supposed to go into circulation until next year. The bills were stolen from an airplane that landed in Philadelphia from Dallas Thursday morning. The plane had been transporting money from the Federal Reserve facility in Dallas."
Saturday, October 13, 2012
Dream big..........
Every trader fantasizes about taking a wild shot and retiring. In Chicago the dream is called the "O'Hare Spread": the idea is to trade into an insanely large position and head for the airport. At the end of the day if the position makes money, you head to Hawaii; if it loses, you're off to South America.
In real life it never works out that way.
Never.
In real life it never works out that way.
Never.
Planning for retirement or bullshitting yourself?
The state of Americans’ retirement accounts is dismal is how ConvergEx's Nick Colas begins his critically important-to-read note on the reality that millions face. According to an early 2012 study by the Employee Benefit Research Institute, Colas notes only 58% of us are currently saving money for retirement – and 60% of those that are have less than $25,000. Thirty percent have less than $1,000. Needless to say, it’s a far cry from the 8x-10x final earnings suggested by most retirement planners. So why are we so far behind? Americans aren’t exactly known for impressive savings habits, but that alone does not explain our poor preparation for retirement. Rather, a general lack of financial literacy, including basic understandings of savings growth and retirement income needs, superseding financial obligations, and basic behavioral finance biases keep us from putting cash away. But if we keep up at this pace, you can expect the ongoing political debate about Social Security to take on new and more strident tones.
Via Nick Colas (and Sarah Miller) of ConvergEx: Hope I Die Before I Get Old
Note From Nick: I don’t remember anything about being 23. Or 24. Or…, well, you get the idea. But understanding the financial decision making of this cohort is a useful exercise, especially when it comes to investing for retirement. Happily, Sarah is in the thick of these decisions and is, in fact, 23. It is pretty easy to see the long shadow of an important social problem from her narrative. If you think the debate over Social Security is raging now, just wait a few years. And now, over to Sarah…
I’ve been at ConvergEx for just over a year now, and I’m happy to say I’ve survived 12 months at my first job in the “real world” after college. I’d like to think I’m a bit smarter than I was when I walked in here last year. When I was given the employee handbook with all the options for healthcare, restaurant discounts, and pre-tax transportation contributions, I admit I had no idea what to choose. So I did what any 22-year-old Millennial child would have done: I called my parents. I figured my mother, who works in healthcare, and my father, the finance professional, would be the best advisors for these kinds of decisions.
After deciding on my options for healthcare and transportation, we finally came to the 401k – something I had certainly heard of, but never really confronted. At 22, retirement savings was nowhere near the top of my priority list; and having just moved into New York City, I was not keen to tuck away part of my paycheck that could have been redirected towards some other expense. After all, wouldn’t that money serve me so much better as a new pair of boots than it would in some account? Part of me is still inclined to say “YES!”. But knowing my parents probably knew more about this than I did, I followed their advice and put a whopping 1% of my paycheck towards the 401k.
Little did I know that only one year into my employment, at the age of 23, I would be farther ahead in my retirement savings plan than millions of American workers. According to a March 2012 survey by the Employee Benefit Research Institute for “retirement confidence”, the majority of Americans are vastly underprepared for retirement, with very few savings or even none at all. A few key takeaways from the report, which can be found here:
•Only 58% of us are even saving for retirement in the first place. Of that group, 60% have less than $25,000 put away, not including home equity or defined benefit plans. Even worse, a full 30% have less than $1,000. A meager 10% have $250,000 or more. (For comparison’s sake, a quick survey of different retirement advisors’ websites showed that the average recommended savings is about 8x-10x final salary – by some estimates, around $1 million)
•While these low savings might be expected of the youngest age cohort, almost half (48%) of workers ages 45 and up have less than $25,000 saved.
•Savings rates and the amount saved are strongly positively correlated to education, income, and health status. 93% of those making more than $75,000 are saving, compared to 35% of those with and income of $35,000 or less.
•Only 38% of all American workers participate in an employer-sponsored retirement savings plan. That said, only 74% are offered this kind of plan. Of those that choose to participate (81%), savings and investments typically total at least $50,000.
•34% of workers that had saved said they have had to dip into their savings to pay for everyday expenses. 22% of retirees claim they’re taking more than they thought they would out of their accounts, depleting their savings even faster than they anticipated.
•Overall it’s a pretty bleak picture. On the whole, Americans are hugely underprepared for retirement, leading quite a few of them (22%) to put off retirement to a later date, or not retire at all (7%).
But why the lack of preparation? Several complementary reasons might reveal the answer:
1. Lack of financial literacy. Americans on the whole are not versed in the ways of financial planning. A study by Lusardi and Mitchell in 2005 found that less than half of a sample of US adults 50 and older was able to answer simple questions about inflation and compounding interest. Another study, by McKensie and Liersch in 2011, showed that a majority of adults misunderstood savings growth: they expected it grew linearly rather than exponentially, therefore underestimating the potential return a small investment could have over several years. When exponential growth of savings was demonstrated, real employees chose to save more for retirement (see the study here). To top it all off, 34% of those surveyed by the EBRI estimated they needed less than $250,000 to retire.
It’s plain correlation, here – the more you know about retirement planning, the more likely you are to do it. Most Americans don’t even calculate how much they might need, leading them to grossly underestimate the costs. A good portion of them (79%, according to the EBRI) also think that Social Security will be a dependable source of income during retirement – much more so than retirees in the 20th century. While that may be true for the Baby Boomers, my generation can’t bank on SS being there when we turn 65. Instead, it’s important that we understand the importance of saving for retirement – or, more likely, the risks of not doing so.
2. Basic behavioral finance biases. Much like the typical stock market investor, retirement savers face several obstructions in the way of their savings goals. A short report from the 2010 Social Security Bulletin, found here, highlights a few of these.
“Ambiguity aversion” is rampant: investors don’t trust products they don’t understand. Given the lack of financial understanding of retirement accounts, then, it’s not surprising that so many Americans shy away from them.
“Heuristics bias” is another classic behavioral finance term found in retirement savings literature. Even if we do choose to save, we may not follow the so-called “rules of thumb” that classical economics assumes in retirement accounts. For example, the traditional allocation shift from equity to bonds as one ages is assumed in classical finance, but according to a 2009 study by VanDerhei, quite a few older investors did not follow this “rule” and lost a significant portion of their savings in 2008.
“Hyperbolic discounting” is also to blame. This is the theory that we sacrifice long-term large gains for short-term immediate gains – we’d rather have an extra $20 in our pockets every month than in an account we don’t touch. This will be a tough one for Americans – the chronic spenders – to overcome.
3. Superseding financial obligations or situation. From weekly groceries to college tuition, savers today are putting other financial obligations ahead of their retirement plans. According to the EBRI survey, 62% of workers consider their current level of debt to be a problem, and may choose to allocate more spending to paying down that debt than to saving for the future. Lower income households are especially prone to this problem: with less income to put away, fewer and fewer of them are saving (down to 35% in 2012 from 49% in 2009).
4. Options. While employer-sponsored retirement savings plans yield high participation rates and above-average savings, not all workers are fortunate enough to have this option. Defined contribution plans such as 401ks and IRAs have overtaken defined benefit plans in the private sector: according to a Department of Labor report from March (found here), a peak of 175,143 private pension plans existed in 1983. That number is now down to 47,137. And as various retirement account studies show, “opt-in” retirement accounts do not draw as many participants as “opt-out” – a clear explanation for Americans’ under-preparedness. This has prompted a few researchers to suggest more active advertisement of plan options for those both with and without employer-sponsored plans to facilitate higher response rates from employees.
The public sector, meanwhile, is still in relatively good shape in terms of defined benefit plans. But while state and local public employees near retirement might expect a decent payout when they become retirees, plans may have to change for public sector employees in the future. Many states – California and Illinois in particular come to mind – have started to consider changes to pension plans given massive cash shortfalls and, arguably, overestimation of growth potential in the pensions (to see a list of expected growth rates in public pension plans by state, see here). Some localities, such as San Diego, have already switched city workers over to defined contribution plans instead.
With these obstacles in place, it’s not necessarily shocking that Americans are financially underprepared for retirement. More financial planning education, or at least a simple demonstration of the importance of saving, and clear options to all workers may help to better prepare us. But a close look at what we expect from our retirement plans – both in the public sector and the private – is essential, given a general misunderstanding of savings growth and payouts on both ends. It’s up to individuals in the private sector to make our own changes, but public sector pensions face quite a host of litigation and regulation to push through.
Most of all, it’s concerning that so many Americans seem to think Social Security is a dependable enough program to fund their retirement. The average payout for a retired worker in August was $1,235.63 – hardly enough to sustain oneself through several years of retirement. My generation will need to come to terms with the fact that by the time we retire, SS may simply not be around. But those who are approaching retirement in the near future need to understand – and plan on the fact – that Social Security cannot be their only source of income in their retirement years. They need to start saving, and fast.
Via Nick Colas (and Sarah Miller) of ConvergEx: Hope I Die Before I Get Old
Note From Nick: I don’t remember anything about being 23. Or 24. Or…, well, you get the idea. But understanding the financial decision making of this cohort is a useful exercise, especially when it comes to investing for retirement. Happily, Sarah is in the thick of these decisions and is, in fact, 23. It is pretty easy to see the long shadow of an important social problem from her narrative. If you think the debate over Social Security is raging now, just wait a few years. And now, over to Sarah…
I’ve been at ConvergEx for just over a year now, and I’m happy to say I’ve survived 12 months at my first job in the “real world” after college. I’d like to think I’m a bit smarter than I was when I walked in here last year. When I was given the employee handbook with all the options for healthcare, restaurant discounts, and pre-tax transportation contributions, I admit I had no idea what to choose. So I did what any 22-year-old Millennial child would have done: I called my parents. I figured my mother, who works in healthcare, and my father, the finance professional, would be the best advisors for these kinds of decisions.
After deciding on my options for healthcare and transportation, we finally came to the 401k – something I had certainly heard of, but never really confronted. At 22, retirement savings was nowhere near the top of my priority list; and having just moved into New York City, I was not keen to tuck away part of my paycheck that could have been redirected towards some other expense. After all, wouldn’t that money serve me so much better as a new pair of boots than it would in some account? Part of me is still inclined to say “YES!”. But knowing my parents probably knew more about this than I did, I followed their advice and put a whopping 1% of my paycheck towards the 401k.
Little did I know that only one year into my employment, at the age of 23, I would be farther ahead in my retirement savings plan than millions of American workers. According to a March 2012 survey by the Employee Benefit Research Institute for “retirement confidence”, the majority of Americans are vastly underprepared for retirement, with very few savings or even none at all. A few key takeaways from the report, which can be found here:
•Only 58% of us are even saving for retirement in the first place. Of that group, 60% have less than $25,000 put away, not including home equity or defined benefit plans. Even worse, a full 30% have less than $1,000. A meager 10% have $250,000 or more. (For comparison’s sake, a quick survey of different retirement advisors’ websites showed that the average recommended savings is about 8x-10x final salary – by some estimates, around $1 million)
•While these low savings might be expected of the youngest age cohort, almost half (48%) of workers ages 45 and up have less than $25,000 saved.
•Savings rates and the amount saved are strongly positively correlated to education, income, and health status. 93% of those making more than $75,000 are saving, compared to 35% of those with and income of $35,000 or less.
•Only 38% of all American workers participate in an employer-sponsored retirement savings plan. That said, only 74% are offered this kind of plan. Of those that choose to participate (81%), savings and investments typically total at least $50,000.
•34% of workers that had saved said they have had to dip into their savings to pay for everyday expenses. 22% of retirees claim they’re taking more than they thought they would out of their accounts, depleting their savings even faster than they anticipated.
•Overall it’s a pretty bleak picture. On the whole, Americans are hugely underprepared for retirement, leading quite a few of them (22%) to put off retirement to a later date, or not retire at all (7%).
But why the lack of preparation? Several complementary reasons might reveal the answer:
1. Lack of financial literacy. Americans on the whole are not versed in the ways of financial planning. A study by Lusardi and Mitchell in 2005 found that less than half of a sample of US adults 50 and older was able to answer simple questions about inflation and compounding interest. Another study, by McKensie and Liersch in 2011, showed that a majority of adults misunderstood savings growth: they expected it grew linearly rather than exponentially, therefore underestimating the potential return a small investment could have over several years. When exponential growth of savings was demonstrated, real employees chose to save more for retirement (see the study here). To top it all off, 34% of those surveyed by the EBRI estimated they needed less than $250,000 to retire.
It’s plain correlation, here – the more you know about retirement planning, the more likely you are to do it. Most Americans don’t even calculate how much they might need, leading them to grossly underestimate the costs. A good portion of them (79%, according to the EBRI) also think that Social Security will be a dependable source of income during retirement – much more so than retirees in the 20th century. While that may be true for the Baby Boomers, my generation can’t bank on SS being there when we turn 65. Instead, it’s important that we understand the importance of saving for retirement – or, more likely, the risks of not doing so.
2. Basic behavioral finance biases. Much like the typical stock market investor, retirement savers face several obstructions in the way of their savings goals. A short report from the 2010 Social Security Bulletin, found here, highlights a few of these.
“Ambiguity aversion” is rampant: investors don’t trust products they don’t understand. Given the lack of financial understanding of retirement accounts, then, it’s not surprising that so many Americans shy away from them.
“Heuristics bias” is another classic behavioral finance term found in retirement savings literature. Even if we do choose to save, we may not follow the so-called “rules of thumb” that classical economics assumes in retirement accounts. For example, the traditional allocation shift from equity to bonds as one ages is assumed in classical finance, but according to a 2009 study by VanDerhei, quite a few older investors did not follow this “rule” and lost a significant portion of their savings in 2008.
“Hyperbolic discounting” is also to blame. This is the theory that we sacrifice long-term large gains for short-term immediate gains – we’d rather have an extra $20 in our pockets every month than in an account we don’t touch. This will be a tough one for Americans – the chronic spenders – to overcome.
3. Superseding financial obligations or situation. From weekly groceries to college tuition, savers today are putting other financial obligations ahead of their retirement plans. According to the EBRI survey, 62% of workers consider their current level of debt to be a problem, and may choose to allocate more spending to paying down that debt than to saving for the future. Lower income households are especially prone to this problem: with less income to put away, fewer and fewer of them are saving (down to 35% in 2012 from 49% in 2009).
4. Options. While employer-sponsored retirement savings plans yield high participation rates and above-average savings, not all workers are fortunate enough to have this option. Defined contribution plans such as 401ks and IRAs have overtaken defined benefit plans in the private sector: according to a Department of Labor report from March (found here), a peak of 175,143 private pension plans existed in 1983. That number is now down to 47,137. And as various retirement account studies show, “opt-in” retirement accounts do not draw as many participants as “opt-out” – a clear explanation for Americans’ under-preparedness. This has prompted a few researchers to suggest more active advertisement of plan options for those both with and without employer-sponsored plans to facilitate higher response rates from employees.
The public sector, meanwhile, is still in relatively good shape in terms of defined benefit plans. But while state and local public employees near retirement might expect a decent payout when they become retirees, plans may have to change for public sector employees in the future. Many states – California and Illinois in particular come to mind – have started to consider changes to pension plans given massive cash shortfalls and, arguably, overestimation of growth potential in the pensions (to see a list of expected growth rates in public pension plans by state, see here). Some localities, such as San Diego, have already switched city workers over to defined contribution plans instead.
With these obstacles in place, it’s not necessarily shocking that Americans are financially underprepared for retirement. More financial planning education, or at least a simple demonstration of the importance of saving, and clear options to all workers may help to better prepare us. But a close look at what we expect from our retirement plans – both in the public sector and the private – is essential, given a general misunderstanding of savings growth and payouts on both ends. It’s up to individuals in the private sector to make our own changes, but public sector pensions face quite a host of litigation and regulation to push through.
Most of all, it’s concerning that so many Americans seem to think Social Security is a dependable enough program to fund their retirement. The average payout for a retired worker in August was $1,235.63 – hardly enough to sustain oneself through several years of retirement. My generation will need to come to terms with the fact that by the time we retire, SS may simply not be around. But those who are approaching retirement in the near future need to understand – and plan on the fact – that Social Security cannot be their only source of income in their retirement years. They need to start saving, and fast.
Wednesday, October 10, 2012

Tuesday, October 09, 2012


Thursday, October 04, 2012
If I had a genie in a bottle..........
My wish would be that President Mitt Romney would allow Harry M. Markopolos to lead the United States Securities & Exchange Commission. Harry is a former securities industry executive and independent financial fraud investigator for institutional investors and others seeking forensic accounting expertise.
Just Like Custers Last Stand!!
The Massacre in Denver last night was a beautiful thing for Americans who think like Dean Parisian. You saw the results of too many nights in Vegas! Unprepared without a plan. Just like the day he took office. All hat, no cowboy.
Barry got stomped like a narc at a biker rally! Go Mitt!
Barry got stomped like a narc at a biker rally! Go Mitt!
Wednesday, October 03, 2012
Hey Big Spender! Vick throws it away..........
Eagles quarterback Michael Vick has filed court documents that show he spent more than $29 million since filing for bankruptcy in 2008.
During the four-year period, Vick had income of about $31 million from his Eagles salary, endorsements and business ventures, TMZ said, citing the documents.
Vick paid out a total of $29.6 million — $10.9 million in taxes, $9.2 million to creditors, $2.7 million to lawyers and accountants and $6.8 million in child support and living expenses, according to the documents.
The former Atlanta Falcon still has $1.5 million left, and that’s not counting a new contract he signed with the Eagles last year that is worth a reported $100 million, $40 million of which is guaranteed.
Vick’s financial troubles stem from his dogfighting conviction and 18 months he spent in federal prison from 2007-2009. He signed with the Eagles in 2009.
During the four-year period, Vick had income of about $31 million from his Eagles salary, endorsements and business ventures, TMZ said, citing the documents.
Vick paid out a total of $29.6 million — $10.9 million in taxes, $9.2 million to creditors, $2.7 million to lawyers and accountants and $6.8 million in child support and living expenses, according to the documents.
The former Atlanta Falcon still has $1.5 million left, and that’s not counting a new contract he signed with the Eagles last year that is worth a reported $100 million, $40 million of which is guaranteed.
Vick’s financial troubles stem from his dogfighting conviction and 18 months he spent in federal prison from 2007-2009. He signed with the Eagles in 2009.
Tuesday, October 02, 2012
This is your mirror talking, take heed
The policy of the Status Quo since 2008 boils down to this assumption:
if we prop up an artificial economy long enough, it will magically become real.
This is an extraordinary assumption: that the process of artifice will
result in artifice becoming real. This is the equivalent of a dysfunctional
family presenting an artificial facade of happiness to the external world and
expecting that fraud to conjure up real happiness. We all know it doesn't work
that way; rather, the dysfunctional family that expends its resources supporting
a phony facade is living a lie that only increases its instability.
The U.S. economy is riddled with artifice: millions of people who recently generated income from their labor have gamed the system and are now "disabled for life." Millions more are living in a bank-enabled fantasy of free housing. Millions more are living off borrowed money: student loans, money the government has borrowed and dispensed as transfer payments, etc. Assets are artificially propped up lest a banking sector with insufficient collateral be revealed as structurally insolvent. It's not difficult to predict an eventual spike of instability in such a system; the only difficulty is predicting the date of the instability. Hiding a broken, dysfunctional economy behind a facade of artifice and illusion can't fix what's broken, it only adds to the system's systemic instability as resources that could have gone to actually fix things are squandered on propping up phony facades of "growth" and "health."
The U.S. economy is riddled with artifice: millions of people who recently generated income from their labor have gamed the system and are now "disabled for life." Millions more are living in a bank-enabled fantasy of free housing. Millions more are living off borrowed money: student loans, money the government has borrowed and dispensed as transfer payments, etc. Assets are artificially propped up lest a banking sector with insufficient collateral be revealed as structurally insolvent. It's not difficult to predict an eventual spike of instability in such a system; the only difficulty is predicting the date of the instability. Hiding a broken, dysfunctional economy behind a facade of artifice and illusion can't fix what's broken, it only adds to the system's systemic instability as resources that could have gone to actually fix things are squandered on propping up phony facades of "growth" and "health."
Monday, October 01, 2012
Tom Lee, ugh.....
Listening to Mr. Tom Lee with JP Morgan on CNBC's Halftime Report reminds me of President Obama.
All bullshit, not a shred of truth.
All bullshit, not a shred of truth.
October 1, 2012
47% of Americans are not having a discussion about economics
today.
They are talking on their "free phones" that purchased their loyalty,
(dependence).
Subscribe to:
Posts (Atom)